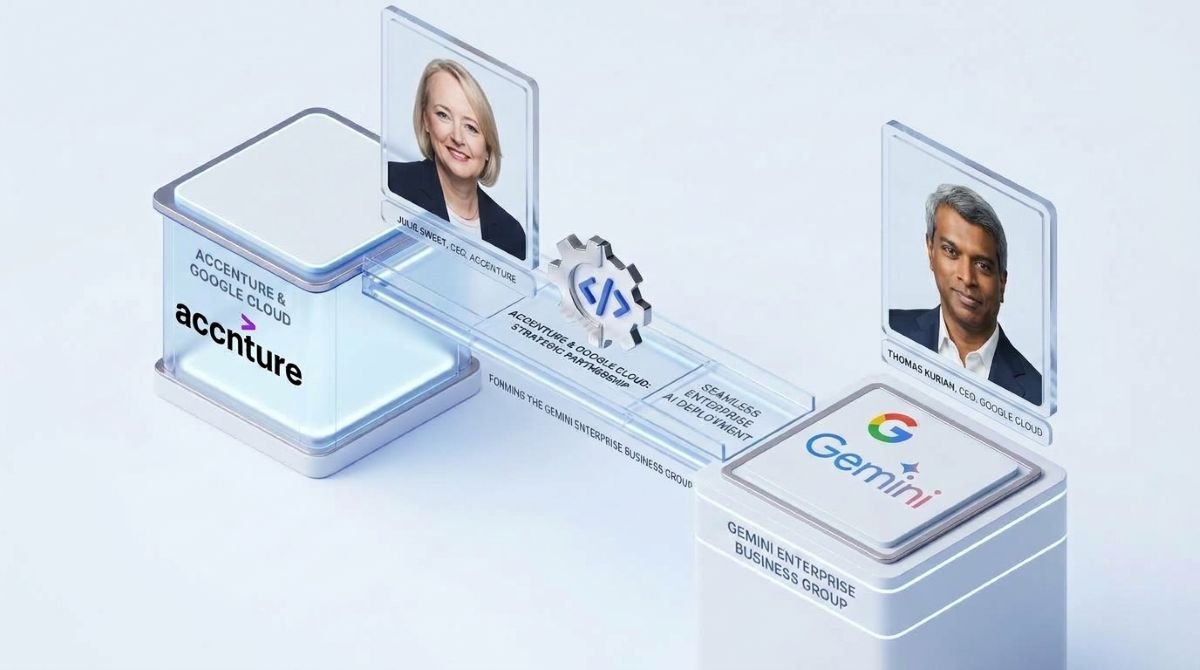
Google Cloud holds roughly 6 p.c of enterprise AI spending amongst U.S. companies. Anthropic and OpenAI collectively account for greater than 80 p.c. The brand new Accenture Gemini Enterprise Enterprise Group is Google’s most direct response to that hole but.
What the Partnership Really Includes
Introduced September 8, the Gemini Enterprise Enterprise Group deploys as much as 1,000 Accenture forward-deployed engineers (FDEs) instantly into enterprise environments to construct and run manufacturing AI purposes on Google’s Gemini platform. These will not be consultants submitting transformation roadmaps from the surface. FDEs embed inside consumer organizations, write manufacturing code, and keep accountable by means of the total deployment lifecycle.
The group attracts from Accenture’s current pool of roughly 50,000 Google Cloud-certified professionals and provides proprietary accelerators and implementation frameworks constructed particularly for Gemini deployments. The aim is to compress the hole between “we evaluated this mannequin” and “this mannequin is working in manufacturing and measurably bettering outcomes.”
A YouTube deployment already exhibits what that appears like in apply. Utilizing Accenture’s implementation, YouTube achieved an 11 p.c enchancment in buyer sentiment scores and a 37 p.c discount in common deal with time throughout NFL Sunday Ticket demand surges. These outcomes emerged from an actual manufacturing atmosphere underneath actual visitors circumstances.
Google’s Precise Drawback
Google Cloud posted $24.8 billion in Q2 2026 income, and Alphabet carries $811 billion in buy commitments as of June 30. The capital funding in AI infrastructure is staggering. The enterprise market share is just not preserving tempo.
Ramp spending information places Google at roughly 6 p.c of enterprise AI procurement amongst U.S. prospects. That determine measures the place enterprise groups are literally writing checks, not which fashions present up in experiments or sandboxes. Anthropic sits at 43.5 p.c. OpenAI at 39.7 p.c. Microsoft, Amazon, and others have all moved to lock in deployment capability by means of their very own FDE-style items this 12 months. Google was not forward of this pattern.
Accenture adjustments the maths in a particular means. When an enterprise purchaser is selecting between AI distributors with comparable mannequin efficiency, the deciding issue more and more comes right down to implementation confidence: who can transfer us from pilot to manufacturing with out burning two years and a number of failed initiatives? Accenture’s scale, its current Google Cloud certification base, and its sector-specific playbooks give Google a reputable reply to that query in accounts the place Google in any other case lacked one.
Google Cloud CEO Thomas Kurian framed the partnership plainly: “Deploying agentic AI is a high precedence for enterprises at this time, and this considerably expands experience accessible.” That may be a candid acknowledgment that experience availability, not mannequin functionality, is the constraint.
Why Consulting Turned a Cloud Vendor Weapon
The FDE mannequin is just not new. What’s new is how aggressively the key cloud distributors are competing for consulting and techniques integrator relationships as a major aggressive lever.
The underlying logic is simple. Enterprise AI adoption didn’t stall as a result of the fashions have been insufficient. It stalled as a result of most organizations lack the engineering capability and institutional data to run manufacturing AI deployments reliably. Constructing an incredible mannequin solves a unique drawback than serving to a producer combine agentic AI into its provide chain operations, or serving to a monetary providers agency push an AI compliance software previous authorized evaluation and into stay workflows.
The businesses that constructed implementation muscle early are producing measurable outcomes. Those that stayed in pilot mode are watching the hole widen. That efficiency differential is now seen sufficient on the govt degree to launch price range, and price range launch is what makes consulting relationships commercially important for cloud distributors.
The August partnership between ServiceNow and Tech Mahindra focused the identical transition level, framing the deal explicitly round “production-ready enterprise AI at scale.” Two main consulting-aligned bulletins in consecutive months, from two totally different cloud vendor ecosystems, aimed on the identical bottleneck, sign a coordinated shift throughout the trade fairly than remoted strikes by particular person gamers.
What Accenture Will get Out of This
Accenture’s strategic place is totally different from Google’s. The agency is just not attempting to enhance its infrastructure market share. It’s constructing a sturdy aggressive moat round supply experience at a second when supply experience is turning into extra worthwhile than mannequin entry.
Cloud distributors will hold releasing extra succesful fashions. Mannequin entry will stay broadly accessible. What is not going to commoditize rapidly is the flexibility to take these fashions into a fancy enterprise atmosphere, combine them with current information infrastructure, handle change on the organizational degree, and produce outcomes that survive contact with actual operations. That functionality takes years to construct at scale, and Accenture has it.
Being designated as Google’s major supply automobile for Gemini at scale places Accenture able rivals can not simply replicate by means of a partnership announcement alone.
The Supply Hole Is the Aggressive Battleground
The hyperscalers have spent 5 years competing on mannequin high quality, infrastructure scale, and pricing. The enterprise AI competitors in 2026 is working on a unique axis: who can truly get this deployed, and how briskly.
The Accenture-Google group is a structural guess that the majority enterprises haven’t solved that drawback internally and can pay to resolve it externally. Provided that enterprise AI spending is concentrated closely within the fingers of distributors who’ve constructed or partnered for robust deployment capability, the guess appears to be like well-placed. Whether or not 1,000 FDEs strikes Google’s 6 p.c share meaningfully is a query that can take a number of quarters to reply. The course of the logic, although, is evident sufficient.
Google Cloud holds roughly 6 p.c of enterprise AI spending amongst U.S. companies. Anthropic and OpenAI collectively account for greater than 80 p.c. The brand new Accenture Gemini Enterprise Enterprise Group is Google’s most direct response to that hole but.
What the Partnership Really Includes
Introduced September 8, the Gemini Enterprise Enterprise Group deploys as much as 1,000 Accenture forward-deployed engineers (FDEs) instantly into enterprise environments to construct and run manufacturing AI purposes on Google’s Gemini platform. These will not be consultants submitting transformation roadmaps from the surface. FDEs embed inside consumer organizations, write manufacturing code, and keep accountable by means of the total deployment lifecycle.
The group attracts from Accenture’s current pool of roughly 50,000 Google Cloud-certified professionals and provides proprietary accelerators and implementation frameworks constructed particularly for Gemini deployments. The aim is to compress the hole between “we evaluated this mannequin” and “this mannequin is working in manufacturing and measurably bettering outcomes.”
A YouTube deployment already exhibits what that appears like in apply. Utilizing Accenture’s implementation, YouTube achieved an 11 p.c enchancment in buyer sentiment scores and a 37 p.c discount in common deal with time throughout NFL Sunday Ticket demand surges. These outcomes emerged from an actual manufacturing atmosphere underneath actual visitors circumstances.
Google’s Precise Drawback
Google Cloud posted $24.8 billion in Q2 2026 income, and Alphabet carries $811 billion in buy commitments as of June 30. The capital funding in AI infrastructure is staggering. The enterprise market share is just not preserving tempo.
Ramp spending information places Google at roughly 6 p.c of enterprise AI procurement amongst U.S. prospects. That determine measures the place enterprise groups are literally writing checks, not which fashions present up in experiments or sandboxes. Anthropic sits at 43.5 p.c. OpenAI at 39.7 p.c. Microsoft, Amazon, and others have all moved to lock in deployment capability by means of their very own FDE-style items this 12 months. Google was not forward of this pattern.
Accenture adjustments the maths in a particular means. When an enterprise purchaser is selecting between AI distributors with comparable mannequin efficiency, the deciding issue more and more comes right down to implementation confidence: who can transfer us from pilot to manufacturing with out burning two years and a number of failed initiatives? Accenture’s scale, its current Google Cloud certification base, and its sector-specific playbooks give Google a reputable reply to that query in accounts the place Google in any other case lacked one.
Google Cloud CEO Thomas Kurian framed the partnership plainly: “Deploying agentic AI is a high precedence for enterprises at this time, and this considerably expands experience accessible.” That may be a candid acknowledgment that experience availability, not mannequin functionality, is the constraint.
Why Consulting Turned a Cloud Vendor Weapon
The FDE mannequin is just not new. What’s new is how aggressively the key cloud distributors are competing for consulting and techniques integrator relationships as a major aggressive lever.
The underlying logic is simple. Enterprise AI adoption didn’t stall as a result of the fashions have been insufficient. It stalled as a result of most organizations lack the engineering capability and institutional data to run manufacturing AI deployments reliably. Constructing an incredible mannequin solves a unique drawback than serving to a producer combine agentic AI into its provide chain operations, or serving to a monetary providers agency push an AI compliance software previous authorized evaluation and into stay workflows.
The businesses that constructed implementation muscle early are producing measurable outcomes. Those that stayed in pilot mode are watching the hole widen. That efficiency differential is now seen sufficient on the govt degree to launch price range, and price range launch is what makes consulting relationships commercially important for cloud distributors.
The August partnership between ServiceNow and Tech Mahindra focused the identical transition level, framing the deal explicitly round “production-ready enterprise AI at scale.” Two main consulting-aligned bulletins in consecutive months, from two totally different cloud vendor ecosystems, aimed on the identical bottleneck, sign a coordinated shift throughout the trade fairly than remoted strikes by particular person gamers.
What Accenture Will get Out of This
Accenture’s strategic place is totally different from Google’s. The agency is just not attempting to enhance its infrastructure market share. It’s constructing a sturdy aggressive moat round supply experience at a second when supply experience is turning into extra worthwhile than mannequin entry.
Cloud distributors will hold releasing extra succesful fashions. Mannequin entry will stay broadly accessible. What is not going to commoditize rapidly is the flexibility to take these fashions into a fancy enterprise atmosphere, combine them with current information infrastructure, handle change on the organizational degree, and produce outcomes that survive contact with actual operations. That functionality takes years to construct at scale, and Accenture has it.
Being designated as Google’s major supply automobile for Gemini at scale places Accenture able rivals can not simply replicate by means of a partnership announcement alone.
The Supply Hole Is the Aggressive Battleground
The hyperscalers have spent 5 years competing on mannequin high quality, infrastructure scale, and pricing. The enterprise AI competitors in 2026 is working on a unique axis: who can truly get this deployed, and how briskly.
The Accenture-Google group is a structural guess that the majority enterprises haven’t solved that drawback internally and can pay to resolve it externally. Provided that enterprise AI spending is concentrated closely within the fingers of distributors who’ve constructed or partnered for robust deployment capability, the guess appears to be like well-placed. Whether or not 1,000 FDEs strikes Google’s 6 p.c share meaningfully is a query that can take a number of quarters to reply. The course of the logic, although, is evident sufficient.