

Bitcoin’s quarter-end liquidity sign modifications path relying on which reserve measure is used. Federal Reserve knowledge launched Oct. 1 present financial institution reserves falling $88.236 billion between Sept. 23 and Sept. 30 Wednesday snapshots, whereas their weekly common rose $17.897 billion.
Reserves are balances banks maintain on the Federal Reserve to make and obtain funds. Their stage issues for greenback financing, however a reserve chart alone can’t set up whether or not stress reached Bitcoin. The balance-sheet decline is basically accounted for by Treasury money and reverse repos, predominantly involving overseas official accounts. September 30’s median price of Treasury-backed in a single day borrowing was 3.90%, inside the vary of the 5 newest noticed readings.
September’s quarter-end due to this fact provides a take a look at of the measurements behind a liquidity thesis. An endpoint steadiness, a mean steadiness and a funding value describe totally different facets of the system. Treating them as interchangeable can flip the identical week into opposing market indicators.
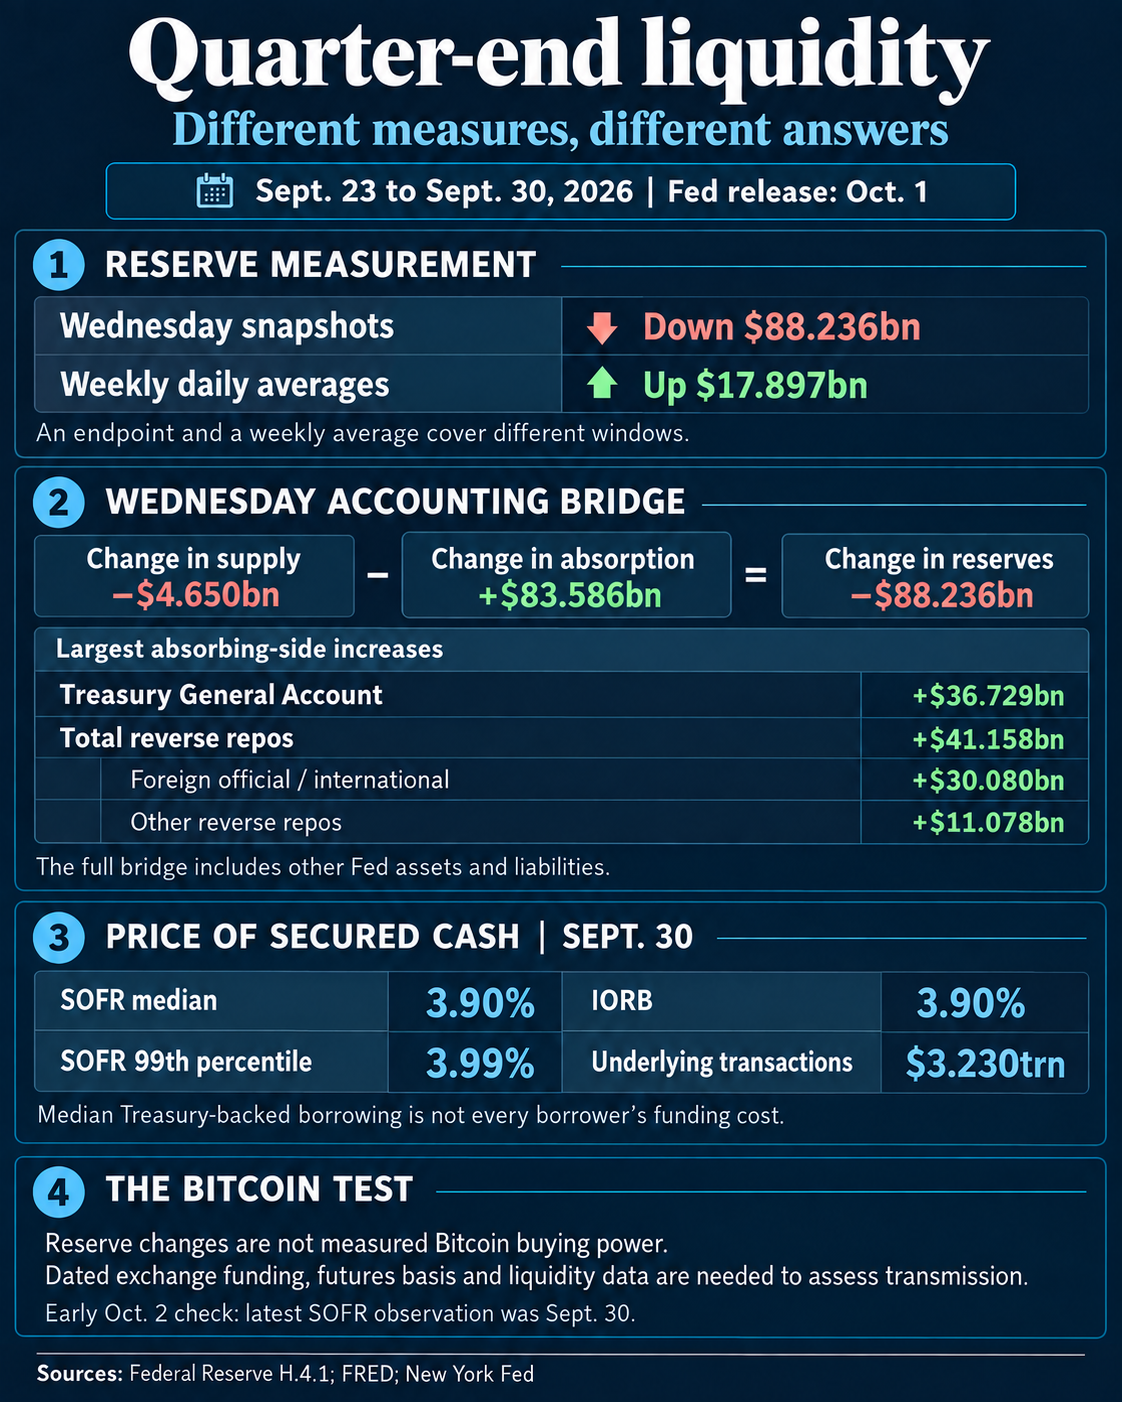
The Wednesday reserve sequence fell from $2.969922 trillion on Sept. 23 to $2.881686 trillion on Sept. 30. The weekly-average sequence rose from $2.930193 trillion to $2.948090 trillion for the weeks ending on these dates.
Each readings come from the Fed’s H.4.1 launch. One compares balances on two Wednesdays; the opposite compares averages of day by day figures throughout two weeks. A decrease remaining commentary can coexist with a better common, as a result of the readings cowl totally different time home windows.
| Measure | Sept. 23 | Sept. 30 | Change |
|---|---|---|---|
| Wednesday reserve balances | $2.969922 trillion | $2.881686 trillion | Down $88.236 billion |
| Weekly-average reserve balances | $2.930193 trillion | $2.948090 trillion | Up $17.897 billion |
The Treasury Normal Account, the federal government’s account on the Fed, illustrates the identical downside. Its Wednesday steadiness rose $36.729 billion to $984.046 billion. Its weekly common fell $28.410 billion to $948.674 billion.
Mixing the Wednesday reserve decline with the typical Treasury decline would mix observations from totally different home windows. It might obscure the very money motion an investor is making an attempt to clarify. A chart labeled “weekly” nonetheless wants a second query: is every level a weekly common or a steadiness noticed as soon as per week?
The endpoint captures the quarter-end place. The common describes the extent throughout the week. Neither offers a whole day by day path or proves how persistent the final-day place will likely be. For a Bitcoin liquidity argument, selecting the window modifications the proof earlier than any value forecast enters the dialogue.
The place the Wednesday reserve decline went
The Oct. 1 H.4.1 launch and earlier launch present an accounting bridge. Between the 2 Wednesday observations, elements supplying reserves fell $4.650 billion, whereas elements absorbing funds exterior reserve balances rose $83.586 billion. Collectively, these modifications reconcile the $88.236 billion reserve decline.
Treasury money was a significant a part of the absorbing facet. Whole reverse repos have been one other: they rose $41.158 billion to $361.883 billion. However most of that reverse-repo steadiness belonged to overseas official and worldwide accounts, which elevated $30.080 billion to $350.344 billion. The remaining “others” class elevated $11.078 billion to $11.539 billion.
Calling the entire $361.883 billion home in a single day reverse-repo utilization would misidentify each the counterparties and the scale of that facility. The excellence additionally issues for comparisons with charts that subtract a home reverse-repo sequence from Fed belongings: these charts don’t symbolize each legal responsibility transferring on this launch.
Past Treasury money and reverse repos, foreign money in circulation elevated $373 million, different non-reserve deposits rose $3.001 billion, and different liabilities and capital elevated $2.317 billion. A separate Treasury cash-holdings line rose $8 million. These smaller absorbing-side modifications full the $83.586 billion improve, with overseas official deposits and the remaining deposit classes unchanged.
The supplying facet moved too. Outright securities declined $6.491 billion, partly offset by $1.199 billion extra repo agreements and $2.493 billion extra loans. These chosen modifications sit inside the complete accounting bridge; they aren’t its full whole. Treasury securities really rose $5.829 billion whereas mortgage-backed securities fell $12.320 billion, so the holdings didn’t transfer uniformly. The individually introduced consolidated steadiness sheet reported a $4.673 billion decline in whole Fed belongings, a special measure from the $4.650 billion fall in reserve-supplying elements.
The Fed’s clarification of its liabilities units out the mechanism. Receipts into the Treasury account can drain financial institution reserves, whereas Treasury spending can return balances to banks, all else equal. Different Fed belongings and liabilities can offset or reinforce these transfers. Gross bond issuance is due to this fact not an equal-sized withdrawal from reserves, and the noticed TGA improve can’t all be assigned to a selected public sale from these figures alone.
For a similar cause, $88.236 billion much less in financial institution reserves shouldn’t be a measured $88.236 billion lack of cash available for purchase Bitcoin. The accounts set up the place balances modified; a crypto-market impact requires proof of a financing channel.
Funding costs give a special take a look at
On the early Oct. 2 examine, the New York Fed’s newest SOFR commentary nonetheless lined Sept. 30. It was 3.90%, matching the Fed’s curiosity on reserve balances, or IORB. The 5 newest noticed SOFR medians ranged from 3.88% to three.90%.
September 30’s 99th-percentile price was 3.99%, with $3.230 trillion of underlying transactions. SOFR rose from 3.88% the day prior to this, however the quarter-end median was additionally the identical as on Sept. 25 and Sept. 28. That exhibits restricted motion within the median, whereas leaving open pressure in components of the market or amongst debtors with totally different entry to money.
SOFR measures in a single day borrowing towards Treasury securities and is calculated as a volume-weighted median. It describes the center of the noticed greenback quantity, not the speed each borrower might receive. A 99th percentile beneath 4% likewise doesn’t set up that each transaction occurred beneath that stage.
Nor have been Fed lending operations absent. H.4.1 reported $1.2 billion of excellent repo agreements on Sept. 30. The day by day repo-purchase sequence individually recorded $1.2 billion that day and 0 purchases on Oct. 1. An impressive steadiness and a day by day operation quantity stay distinct measures, even when their values match.
Entry is one more reason to look past the median. The standing repo phrases specify a 4.00% price, two day by day operation home windows and a $40 billion proposition restrict per eligible counterparty, per eligible safety kind, per operation. Entry is dependent upon counterparty and collateral eligibility, so the backstop’s phrases can’t show each market participant had prepared entry to money.
October 1 provided a narrower follow-up: home in a single day reverse-repo utilization fell from $11.539 billion to $350 million. That signifies the home facility improve unwound sharply. It doesn’t measure an combination reserve rebound or present that the overseas official pool did the identical. October 1 SOFR was not but out there within the early Oct. 2 snapshot.
What would set up stress reaching Bitcoin?
CryptoSlate’s Sept. 28 settlement preview posed a conditional take a look at of repo and Bitcoin funding after settlement, following its Sept. 21 tax-date protection of falling financial institution balances alongside orderly repo. The brand new reserve comparability provides a cause to look at the measure itself earlier than turning that take a look at right into a market conclusion.
Proof of a dollar-funding squeeze can be stronger if borrowing prices remained elevated relative to the Fed’s settings throughout subsequent observations, with stress seen past one median. Facility utilization and entry circumstances would assist distinguish a short lived quarter-end adjustment from persevering with financing pressure.
A Bitcoin transmission declare wants one other hyperlink: dated trade or instrument-level funding, futures-basis or liquidity observations over a comparable window. Modifications in market depth, credit score availability or positioning might corroborate that hyperlink. Even simultaneous Bitcoin weak spot and better repo charges would go away causation unresolved.
The present reserve and SOFR figures set up neither a Bitcoin financing shock nor its absence. They set up one thing extra particular: the Wednesday reserve decline reconciles with modifications elsewhere within the Fed’s accounts, the weekly common moved in the wrong way, and the newest noticed secured-cash median remained at IORB. Subsequent funding costs and direct Bitcoin financing knowledge can strengthen or weaken the case that the quarter-end balance-sheet motion turned a sustained squeeze.