

A $202 billion U.S. Treasury coupon settlement on Sept. 30 will take a look at in a single day financing at quarter-end. The Federal House Mortgage Financial institution of New York says the market is calm for now however warns that internet new provide might carry repo borrowing charges. Whether or not that strain reaches Bitcoin is a separate, unobserved query.
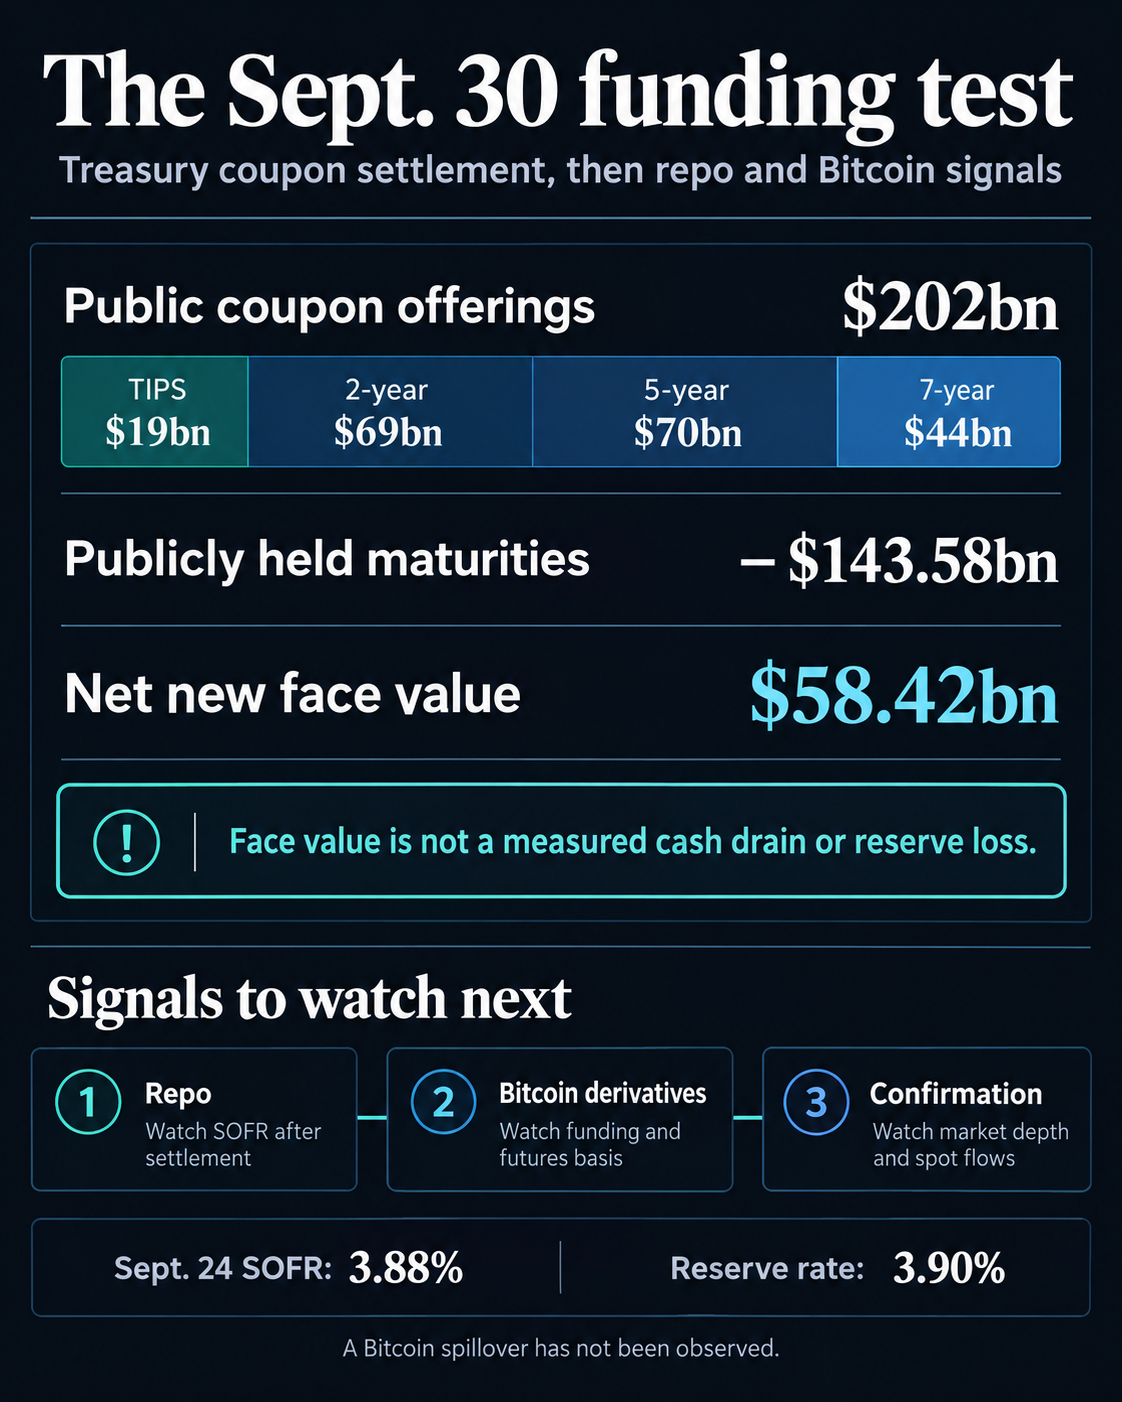
The Treasury calendar places a reopened 10-year inflation-protected bond and two-, five- and seven-year notes on Wednesday’s settlement date. The TIPS, two-year, five-year and seven-year bulletins set public face quantities of $19 billion, $69 billion, $70 billion and $44 billion, respectively, totaling $202 billion.
Treasury additionally estimates $143.58 billion of publicly held coupon debt will mature that day, leaving $58.42 billion of internet new face worth. That could be a measure of securities issued past maturities, not an noticed money drain or fall in financial institution reserves. Public sale costs, inflation changes and Treasury spending can change the money impact. Payments auctioned simply earlier than quarter-end are scheduled to settle Oct. 1, outdoors this coupon determine.
The New York Fed’s present schedule requires roughly $15.6 billion of reinvestment purchases over Sept. 15 to Oct. 14 however no reserve-management purchases. These are completely different operations: the Fed continues changing principal from maturing mortgage securities with Treasury payments, whereas its separate program for including reserves is paused. New York Fed official Roberto Perli mentioned Sept. 22 that reserves appeared ample and funding markets had remained orderly.
Two markets to look at
SOFR, a broad measure of in a single day Treasury-backed borrowing prices, was 3.88% for Sept. 24, the newest accessible pre-event studying as of Sunday. It had been 3.85% on Sept. 18 and 21 and remained under the three.90% fee the Fed pays on financial institution reserves, based on FHLBNY. SOFR had already edged up, although FHLBNY nonetheless described financing as calm.
1 / 4-end SOFR soar that promptly fades could be a weaker sign than strain that persists relative to the Fed’s reserve fee and different repo measures. For a Bitcoin spillover, merchants would additionally search for weakening perpetual-futures funding or a narrowing futures premium, with falling market depth, diminished leverage or weaker spot flows as corroboration. Latest CryptoSlate protection described falling derivatives publicity amid a Treasury-yield shock earlier than this settlement, which can’t be attributed to its repo consequence.
If repo charges and Bitcoin funding stay regular after settlement, the anticipated spillover would lack proof. Even when Bitcoin falls whereas SOFR rises, timing alone wouldn’t present that Treasury financing induced the transfer.