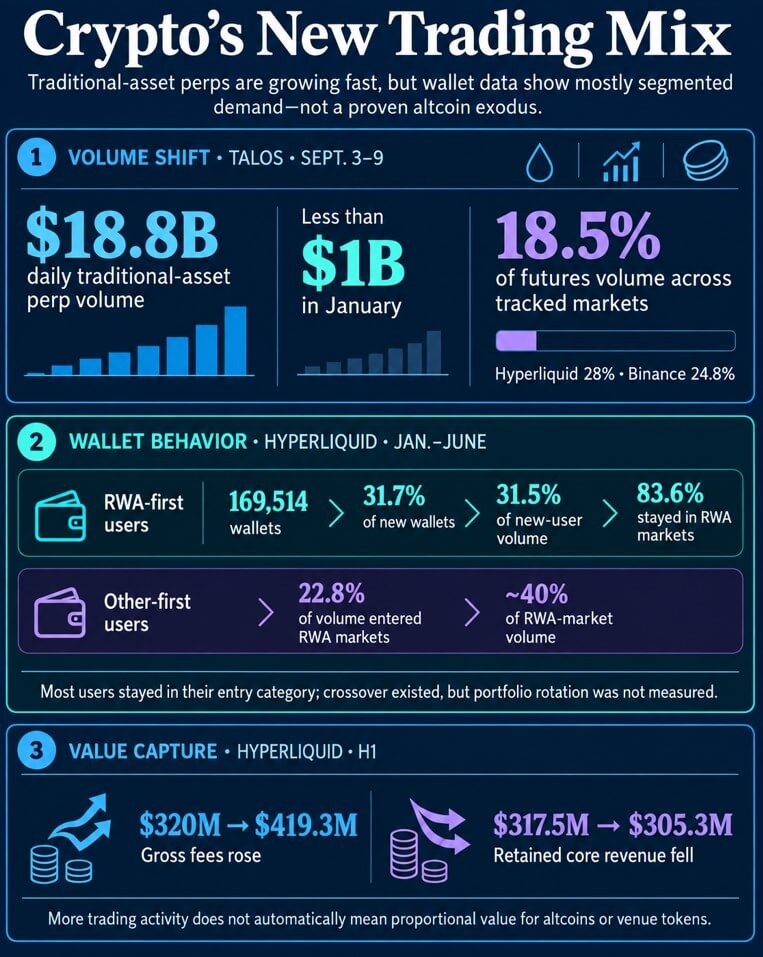
Within the markets Talos tracked, each day quantity in RWA perpetual futures tied to equities, commodities and indices rose from lower than $1 billion in January to $18.8 billion throughout Sept. 3-9. That represented 18.5% of futures quantity throughout these venues.
Crypto exchanges constructed their derivatives companies round perpetual futures, and the identical contract construction now wraps publicity to grease, gold, shares, indices, and pre-IPO corporations.
The Talos information present that crypto-perpetual quantity declined over the comparability interval whereas whole futures exercise in its pattern remained roughly flat, with traditional-asset contracts filling the quantity hole.
The altering product combine creates an actual aggressive menace for altcoins. Merchants not want a brand new token to search out leverage, volatility, or a market that stays open across the clock.
Pockets conduct on Hyperliquid factors to largely separate buyer teams, with a smaller group buying and selling throughout each markets.
Hyperliquid’s merchants largely keep of their lanes
Talos discovered that conventional asset perps represented 28% of futures quantity on Hyperliquid and 24.8% on Binance in its pattern. Oil led the weekly enhance as Brent crossed $100, exhibiting how crypto venues can seize buying and selling round an occasion unrelated to cryptocurrency.
CoinDesk Analysis reported that centralized-exchange quantity rose 12.7% month over month to $4.29 trillion in August. Spot elevated 18.7%, derivatives rose 11.3%, and traditional-asset perpetual quantity elevated 2.37% to $602 billion.
Each traditional-asset and crypto exercise expanded throughout that month. Substitution may nonetheless happen inside a particular venue or account, whereas the combination figures present that the 2 classes can even develop collectively.
Hyperliquid’s HIP-3 framework lets exterior builders deploy markets, together with contracts linked to shares and commodities. DefiLlama divided new wallets into RWA-first and “Different-first” cohorts primarily based in the marketplace of their first Hyperliquid commerce.
From Jan. 1 by means of June 30, DefiLlama categorised 169,514 new wallets as RWA-first. They represented 31.7% of recent wallets and generated $111.6 billion (31.5%) of the buying and selling quantity produced by new customers.
The economics of this acquisition cohort differed sharply from its share of exercise: RWA-first wallets generated solely 8.3% of the primary buying and selling charges paid by new customers within the research.
RWA-first wallets stored 83.6% of their quantity in RWA markets, whereas Different-first wallets, whose first commerce was in crypto or one other non-RWA market, despatched 22.8% of their quantity into RWA markets and produced roughly 40% of RWA-market quantity.
| Group | Buying and selling conduct | Reader takeaway |
|---|---|---|
| RWA-first wallets | 31.7% of recent wallets, 31.5% of new-user quantity | Conventional-asset markets attracted a considerable new cohort, although its capital supply stays unknown |
| RWA-first wallets | 83.6% of quantity stayed in RWA markets | Most traded primarily within the product class they entered by means of |
| Different-first wallets | Roughly 40% of RWA-market quantity | Present crypto-platform customers crossed into conventional belongings, with adjustments to their crypto positions unmeasured |
A DefiLlama follow-up discovered that 80.9% of RWA-first wallets by no means crossed into the opposite market, whereas 82% of Different-first wallets by no means crossed into RWA markets.
Cross-market exercise elevated among the many most frequent merchants who did cross. The consumer base divides into three broad teams: RWA-first wallets that largely stick with these merchandise, crypto-first wallets that largely stick with crypto, and a smaller high-frequency core that treats each as buying and selling alternatives.
Altcoins face a more durable contest for consideration
CryptoRank counted 351 new listings throughout 10 main centralized exchanges within the second quarter, the fewest for the reason that third quarter of 2023. Tokenized belongings accounted for 42 additions, whereas classes related to the earlier speculative cycle misplaced momentum.
Gate was accountable for 573 removals, practically 60% of delistings within the first half. MEXC hardly ever reported delistings and was successfully excluded from that a part of the evaluation.
Inside CryptoRank’s pattern, change priorities modified as one venue’s cleanup dominated removals and reporting gaps restricted the cross-exchange image. RWA buying and selling can’t be blamed for these delistings.
Binance’s tokenized-stock figures additionally present overlap however don’t reveal portfolio rotation. Binance Analysis reported that 58.5% of early bStocks customers additionally used perpetuals, direct equities, or each.
For altcoin holders, the sensible danger is competitors on the margin. Market makers have finite steadiness sheets, exchanges have restricted promotional capability, and merchants have restricted consideration. Acquainted shares and commodities now compete with them inside the identical apps and collateral methods.
Altcoins have a brand new competitor for speculative demand. One other instance is the HIP-3, which lets exterior builders deploy perpetual markets.
Hyperliquid’s charge documentation says deployers could retain as much as 50% of buying and selling charges generated by their belongings. Buying and selling charges directed to the protocol’s Help Fund are transformed routinely into HYPE, Hyperliquid’s native token, and the acquired HYPE is burned.
Solely a portion of builder-market exercise reaches HYPE-related mechanisms. Help Fund burns can scale back token provide, whereas market worth nonetheless is determined by demand, liquidity and the broader market.
Exercise and retained economics can transfer aside
The divergence appeared in first-half figures calculated by 21Shares, which estimated that Hyperliquid’s gross charges rose from $320 million within the first half of 2025 to $419.3 million within the first half of 2026. Its measure of core protocol income, the charge share flowing again to the platform treasury, fell from $317.5 million to $305.3 million.
Gross charges and core income moved in reverse instructions as builder-deployed markets captured a bigger share of exercise.
Crypto perps led the subsequent month-to-month growth, as Hyperliquid’s whole open curiosity rose from $6.6 billion to $8.8 billion in September. In the meantime, HIP-3’s share declined from 34% to 25%.
Conventional asset buying and selling can fill a crypto-volume hole in a single interval and develop alongside crypto in one other. It may well herald new wallets, give current customers extra merchandise, and create charge streams divided among the many protocol, builders, and token-linked mechanisms, making exchanges much less depending on crypto’s cycles.
For altcoins, the result is extra ambiguous. Crypto’s buying and selling rails can thrive even when demand for the belongings that constructed them grows extra slowly.