

Swift’s Blockchain Ledger Goes Stay: What 17 Banks Are Really Testing
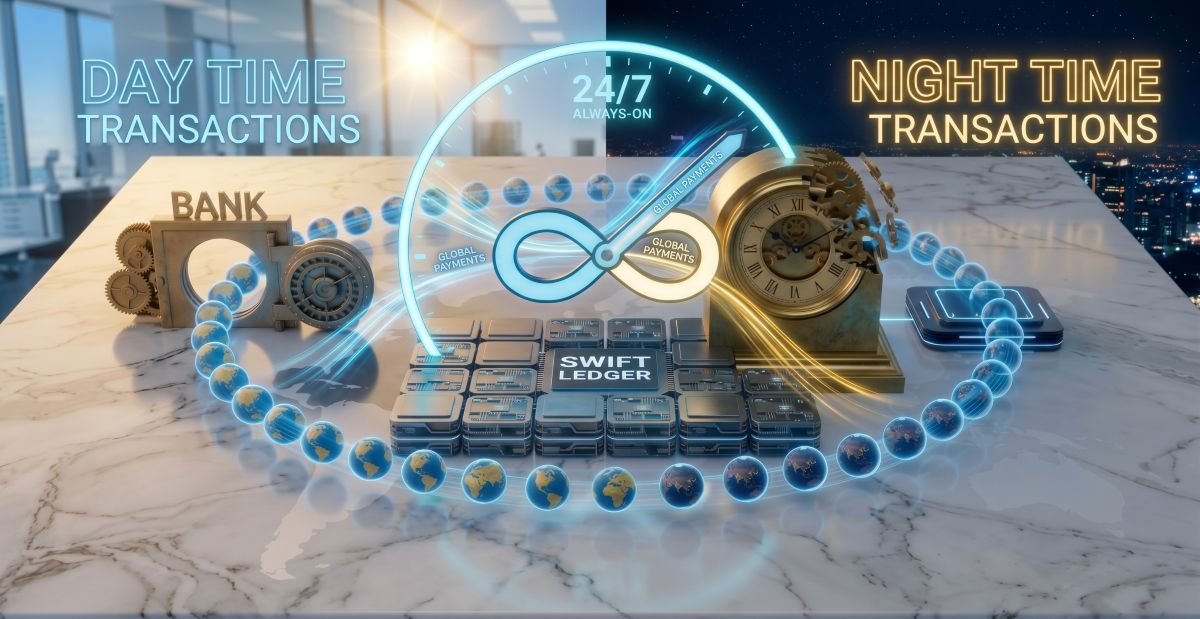
For 50 years, Swift’s job was easy: inform banks the place the cash ought to go, then get out of the way in which. On July 9, 2026, the job modified. A blockchain ledger now sits inside Swift’s infrastructure, and seventeen banks throughout six continents are working actual funds by means of it. The fascinating half isn’t the blockchain. It’s what Swift determined to not contact.
9 Months From Idea to Managed Go-Stay
9 months is quick for a legacy monetary community to maneuver from an concept to a reside pilot. Swift floated the shared-ledger idea at Sibos on September 29, 2025, promising greater than 30 establishments would assist design it, with Consensys behind the preliminary prototype. The construct reached MVP stage on March 30, 2026, working an EVM-compatible structure on Hyperledger Besu. On July 9, Swift known as it prepared for preliminary use and named seventeen banks getting ready to pilot reside transactions.
ANZ, BNP Paribas, BNY, Citi, DBS, First Abu Dhabi Financial institution, FirstRand, HSBC, Itaú Unibanco, Lloyds, Mashreq, MUFG, OCBC, Commonplace Chartered, UBS, UOB and Wells Fargo make up the roster, unfold, Swift says, throughout six continents. Giant world gamers sit alongside custody specialists and regional banks already working established tokenisation applications. The combo reads like a real cross-section, not a handpicked showcase. Swift is cautious with the label too: a managed go-live, not a industrial rollout, with extra performance promised as soon as the part proves out.
An Orchestration Layer, Not a New Forex
So what did Swift activate? Not a foreign money. Swift points no cash on the brand new ledger and has constructed no cryptocurrency. Banks within the pilot challenge tokenised deposits, digital stand-ins for a buyer’s present deposit declare, on ledgers they run individually. Swift’s layer information, sequences and validates the fee commitments shifting between banks, then lets sensible contracts implement the principles.
Right here’s the excellence price sitting with: a tokenised deposit by no means leaves the regulated banking system. A financial institution points it, carries it on the steadiness sheet, and runs it by means of the identical deposit, compliance and danger framework masking each different greenback it holds. A stablecoin normally sits outdoors the banking system solely, backed by reserve property and circulating on public blockchains by means of wallets and exchanges no financial institution controls. Swift’s design retains the cash inside a fringe regulators already know the right way to police.
Thierry Chilosi, Swift’s chief enterprise officer, calls it an extension of “the belief and stability of established finance” into digital cash, with a watch towards programmable-money and agentic-commerce use instances down the road. HSBC, which plans to plug its Tokenised Deposit Service into the ledger, pitches the attraction in blunter phrases: real-time funds throughout time zones, no synthetic cut-offs.
Ethereum Beneath the Hood, With Financial institution-Grade Guardrails
Beneath the hood, the MVP runs on Ethereum Digital Machine-compatible know-how constructed on Hyperledger Besu, an enterprise Ethereum consumer constructed for permissioned networks. Consensys backed the unique 2025 prototype, although Swift’s July launch stops in need of confirming whether or not the agency nonetheless holds the first know-how contract.
The setup doesn’t put Swift on Ethereum’s public mainnet. No financial institution is shopping for Ether to make a fee. The permissioned design borrows smart-contract programmability whereas conserving participation, governance and knowledge visibility locked to vetted establishments. Actual questions stay open: who runs the validating nodes, how knowledge will get partitioned between banks, what occurs when a sensible contract wants a rewrite. The solutions will matter greater than the structure as soon as the pilot strikes previous its first transactions.
Round-the-Clock Entry Is Not Immediate Settlement
Actual-time. Immediate. All the time-on. Swift, HSBC and the remainder of the pilot banks attain for a similar phrases, and none of them has revealed a service-level settlement, a benchmark, or a single corridor-specific timing determine to again it up. The vocabulary describes ambition, not a measurement.
Three clocks run without delay right here, and mixing them up produces a rosier image than the details help. The ledger validates and information a fee dedication quick. A receiving financial institution can launch buyer funds outdoors regular banking hours, in a single day, on a weekend. Closing interbank settlement, in the meantime, nonetheless runs by means of present methods within the present design, and nothing in Swift’s launch ensures the settlement step occurs in seconds.
The hole between funds exhibiting up and the debt clearing for actual raises a query each treasury staff ought to ask earlier than it will get excited: who eats the intraday or weekend credit score publicity if a fee strikes earlier than settlement finishes. No one has answered it publicly but.
Swift, Ripple, Agorá and Fnality Are Racing Towards the Identical Purpose on Totally different Roads
Swift isn’t the one outfit chasing always-on cross-border funds, and the variations between the 4 main makes an attempt say greater than any of the advertising decks.
| Mannequin | Major cash type | Strategy | Present standing |
| Swift shared ledger | Financial institution-issued tokenised deposits | Orchestration layer linked to present rails | Managed preliminary go-live |
| Ripple Funds | Stablecoins, XRP, fiat | Managed digital-asset fee community | Industrial service |
| Undertaking Agorá | Tokenised deposits and central-bank reserves | Shared programmable wholesale platform | Prototype shifting to real-value testing |
| Fnality | Central-bank-backed digital money | Forex-specific DLT fee methods | Sterling system reside; broader community growing |
Ripple sells stablecoins, XRP and fiat by means of a managed fee community constructed outdoors conventional banking rails, with XRP Ledger transactions Ripple says settle in roughly three to 5 seconds. Undertaking Agorá, run by the Financial institution for Worldwide Settlements alongside the Federal Reserve Financial institution of New York and greater than 40 establishments, demonstrated atomic multi-currency settlement combining tokenised central-bank reserves with commercial-bank deposits in a Could 2026 prototype, nonetheless in need of manufacturing. Fnality backs its digital money instantly with funds parked at central banks, tying settlement finality to central-bank cash as an alternative of orchestration between industrial banks.
Not one of the three substitutes for what Swift constructed. Ripple bets on velocity and attain outdoors the present banking system. Agorá bets on redesigning the settlement layer itself. Fnality bets on tying digital money to central-bank cash. Swift’s wager is probably the most conservative of the 4: join the tokenised deposits banks already plan to challenge, and ask none of them to surrender the compliance equipment or Swift connectivity they already run on. In banking, conservative bets are likely to outlast daring ones.
The Payoff for Treasury Groups Is dependent upon What Occurs After the Demo
The improve doesn’t matter to a company treasurer chasing a sooner Monday-morning wire. It issues to at least one working Friday-afternoon payroll for an workplace opening Monday in a special time zone. In a single day and weekend fund motion, sooner intercompany transfers, and a clearer learn on money positions all turn out to be actual as soon as a receiving financial institution can launch funds outdoors typical banking hours.
Banks gained’t profit evenly. World transaction banks already issuing tokenised deposits, HSBC and Citi amongst them, sit closest to the middle of the pilot. Correspondent banks dwelling on charges from gradual, multi-step fee chains face the alternative publicity, and so do fintechs whose complete pitch has been velocity. None of it performs out till the pilot produces actual transaction quantity as an alternative of a handful of showcase funds.
What Swift Hasn’t Revealed Will Resolve Whether or not the Ledger Scales
Swift has not mentioned when the primary reside transaction will occur, which corridors or currencies it covers, what quantity it expects, or how governance works in observe. The worth tag is a clean too, so no person outdoors the seventeen banks can say whether or not the ledger prices much less to run than the correspondent-banking chain it’s supposed to exchange elements of. Regulatory remedy provides a fog on high: no single authority indicators off on a cross-border financial institution ledger, and central banks, prudential supervisors and data-protection regulators throughout a number of jurisdictions will every declare a bit of it.
Swift has tried blockchain earlier than with none of it sticking: a 2017 nostro-reconciliation proof of idea, CBDC interoperability work in 2022 and 2023, neither one scaling previous the lab. What separates the present try is the roster, seventeen reside contributors, and the nine-month dash from idea to managed use. Momentum isn’t proof.
Swift hasn’t moved world banking onto a public blockchain, and it hasn’t changed the settlement methods beneath cross-border funds. What it’s constructed is a bridge: regulated deposits transfer with fewer time-zone constraints, whereas banks preserve the authorized and operational scaffolding they already belief. The subsequent 12 months will present whether or not seventeen banks flip a pilot into actual quantity, or whether or not blockchain’s most credible banking experiment stalls precisely the place each one earlier than it stalled: at proof of idea.